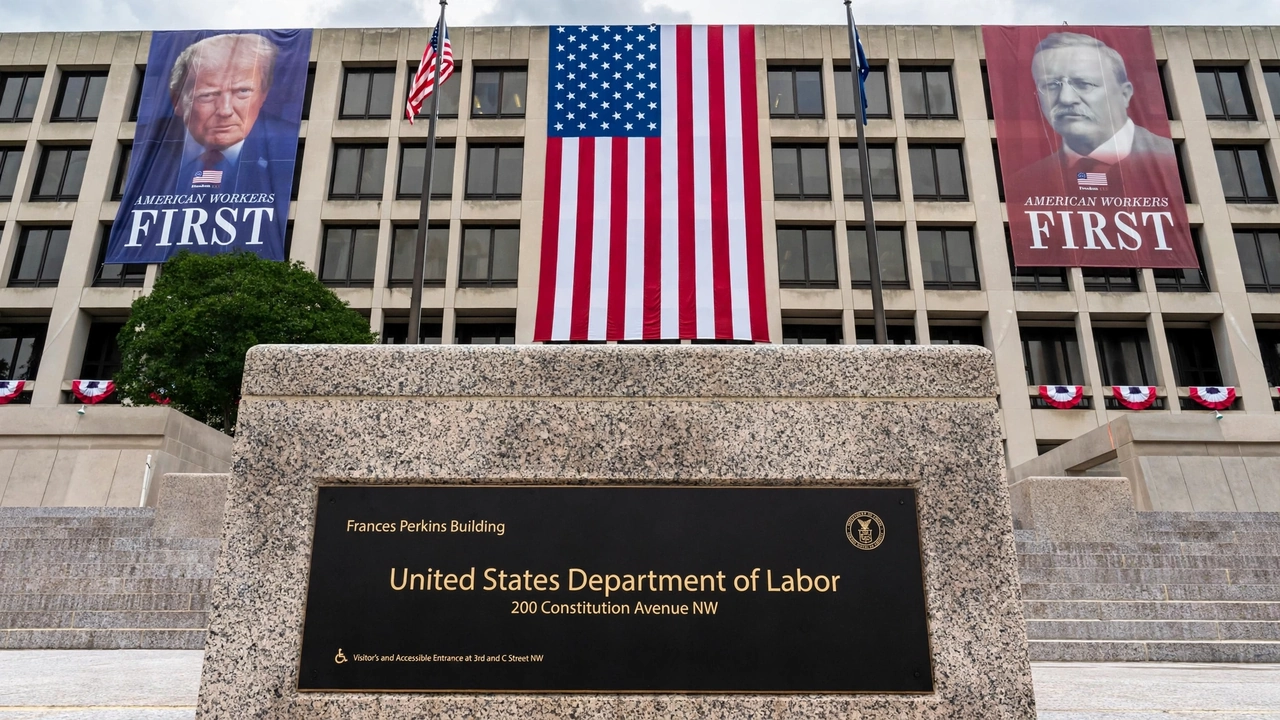
The U.S. September jobs report is due Friday morning with economists expecting payroll growth to slow sharply from August, giving the Federal Reserve a fresh test of labor-market strength less than four weeks before its next interest-rate decision.
The Bureau of Labor Statistics release calendar schedules the September Employment Situation for 8:30 a.m. Eastern Time on October 2. A Reuters survey of economists puts the median forecast at 90,000 additional nonfarm payroll jobs, with unemployment expected to remain at 4.1%. Those numbers are expectations, not official results. The BLS has not yet published the September employment figures.
A 90,000 gain would represent a substantial slowdown from August, when the BLS August Employment Situation report showed payrolls increasing by 162,000 while unemployment held at 4.1%. The August increase was itself unusually strong compared with the average monthly gain of only 31,000 over the previous 12 months.
If the consensus is exactly right, September payroll growth would be 72,000 jobs below August, or about 44% lower, an Investozora calculation using the BLS August figure and the Reuters consensus forecast. That comparison should not be read as an official September result before the BLS release.
The range of economists’ estimates is also unusually wide. Reuters reported forecasts running from roughly 35,000 to 180,000 jobs, showing substantial uncertainty around the headline number.
Recent official labor indicators offer a mixed but relatively stable backdrop. The BLS August Job Openings and Labor Turnover Survey showed 7.1 million job openings, with hires little changed at 5.2 million and layoffs and discharges essentially unchanged at 1.6 million. Separately, the Labor Department’s latest unemployment-insurance report showed initial jobless claims falling to 197,000 in the week ended September 26.
That combination suggests employers have remained cautious about expanding payrolls without producing a broad increase in layoffs. Friday’s report will show whether that pattern carried into September.
The policy implications matter because the Fed has already moved rates higher. On September 16, the Federal Open Market Committee raised its target range by 25 basis points to 3.75%–4.00%, saying economic activity was expanding at a solid pace, job gains had kept pace with the workforce and inflation remained elevated.
The Fed’s accompanying September economic projections put the median unemployment-rate projection at 4.1% for the fourth quarter of 2026, down from 4.3% in June. Officials also projected a median federal funds rate of 4.1% at year-end, up from 3.8% in the June projections.
Given the current 3.75%–4.00% target range, that year-end median is consistent with roughly one additional quarter-point increase in 2026, although the projections are individual policymakers’ assessments of appropriate policy and are not a commitment to another hike.
That is why September’s employment numbers matter beyond the headline payroll count. A report close to the 90,000 consensus with unemployment holding at 4.1% would broadly preserve the labor-market picture incorporated into the Fed’s September projections. A materially stronger or weaker report could instead change how officials assess the balance between persistent inflation and employment conditions.
Investozora’s analysis of the Fed’s September economic projections explains how policymakers simultaneously raised their growth and interest-rate forecasts while lowering their unemployment projection. For the broader mechanism connecting payrolls, unemployment and monetary policy, the Investozora jobs-report and Fed-rate guide provides the longer-term framework.
The next decision comes at the October 27–28 FOMC meeting. Before then, policymakers will receive additional evidence, including September inflation data, meaning Friday’s jobs report will be an important input rather than a standalone signal of what the Fed will ultimately do.