Crude oil prices edged higher Tuesday as Brent crude futures returned above $100 a barrel, with the market balancing renewed security risks around key Middle East shipping routes against evidence that regional oil flows are recovering.
At around 03:30 GMT on October 6, December Brent was quoted at $100.59 a barrel, up 27 cents from Monday’s $100.32 settlement, a gain of about 0.27% calculated from the two prices and broadly consistent with the 0.3% increase reported by Reuters. U.S. West Texas Intermediate was up 30 cents at $89.73.
The move is notable less for its size than for the level being tested. Monday’s Brent settlement had fallen $1.93, or 1.89%, as higher Middle Eastern exports and a new emergency-supply commitment from the Group of Seven reduced some immediate supply concerns. Tuesday’s rebound therefore has not reversed that decline; it shows that crude has remained around the psychologically important $100 threshold even as supply expectations improve.
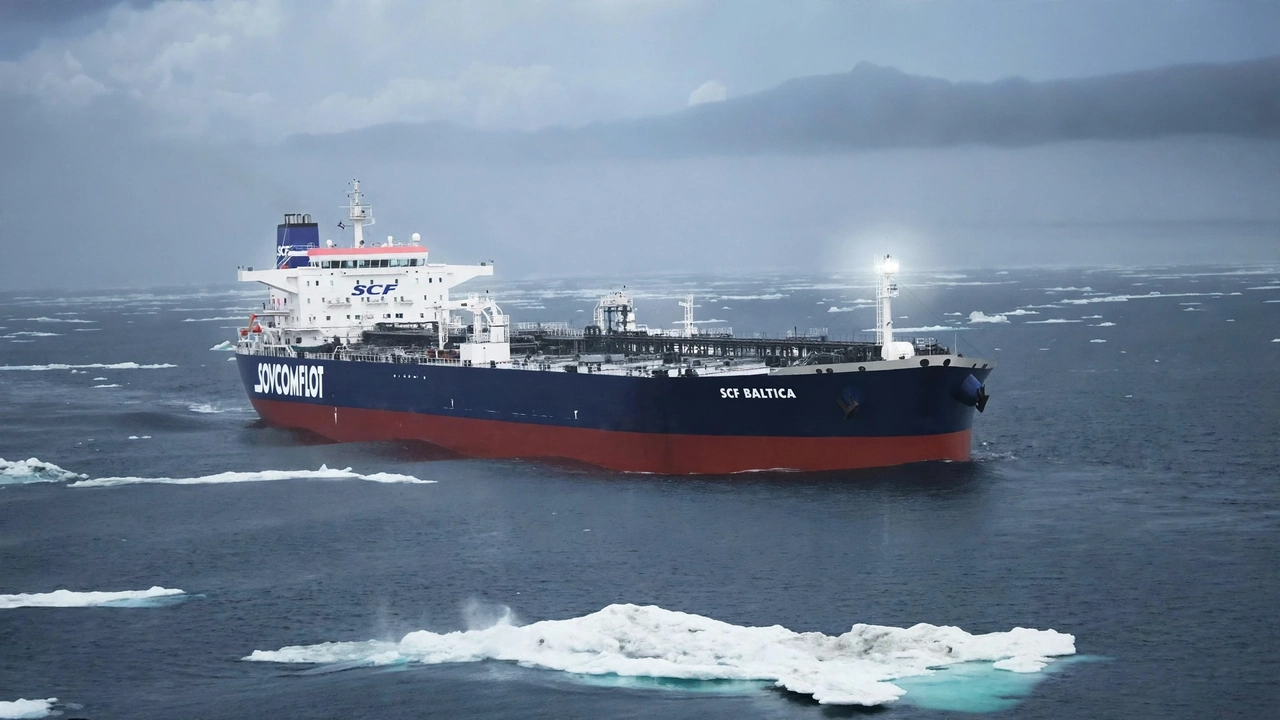
The competing forces are unusually clear. Reuters reported renewed attacks on tankers around the Strait of Hormuz, keeping a security premium in the market, while shipping data showed Middle Eastern crude exports excluding Iran had recovered to more than 81% of pre-war levels in September.
That combination means the market is not simply pricing a supply shortage: it is weighing how reliably barrels can move through disrupted trade routes. Investozora has previously tracked the relationship between Hormuz disruption and crude prices in its coverage of Iran-Hormuz supply risks.
The supply side is also being cushioned by the G7’s emergency response. In its October 2 leaders’ statement, the G7 said it would coordinate through the International Energy Agency a release of 100 million barrels over four months, including a substantial front-loaded diesel release during the first 20 days, while reaffirming that members would avoid energy export restrictions.
OPEC+ is providing another constraint on the supply outlook. On October 4, seven participating countries agreed to maintain their September 2026 required production levels for November, with their next meeting scheduled for November 1. That leaves geopolitical disruptions and actual physical flows as more immediate variables for prices than a fresh production increase from those producers.
The next major U.S. supply datapoint is the Energy Information Administration’s Weekly Petroleum Status Report, normally released Wednesday at 10:30 a.m. Eastern. Inventory, refinery and petroleum-product data will provide a fresh test of whether improving supply availability is becoming visible in U.S. balances while Middle East shipping risks remain elevated.