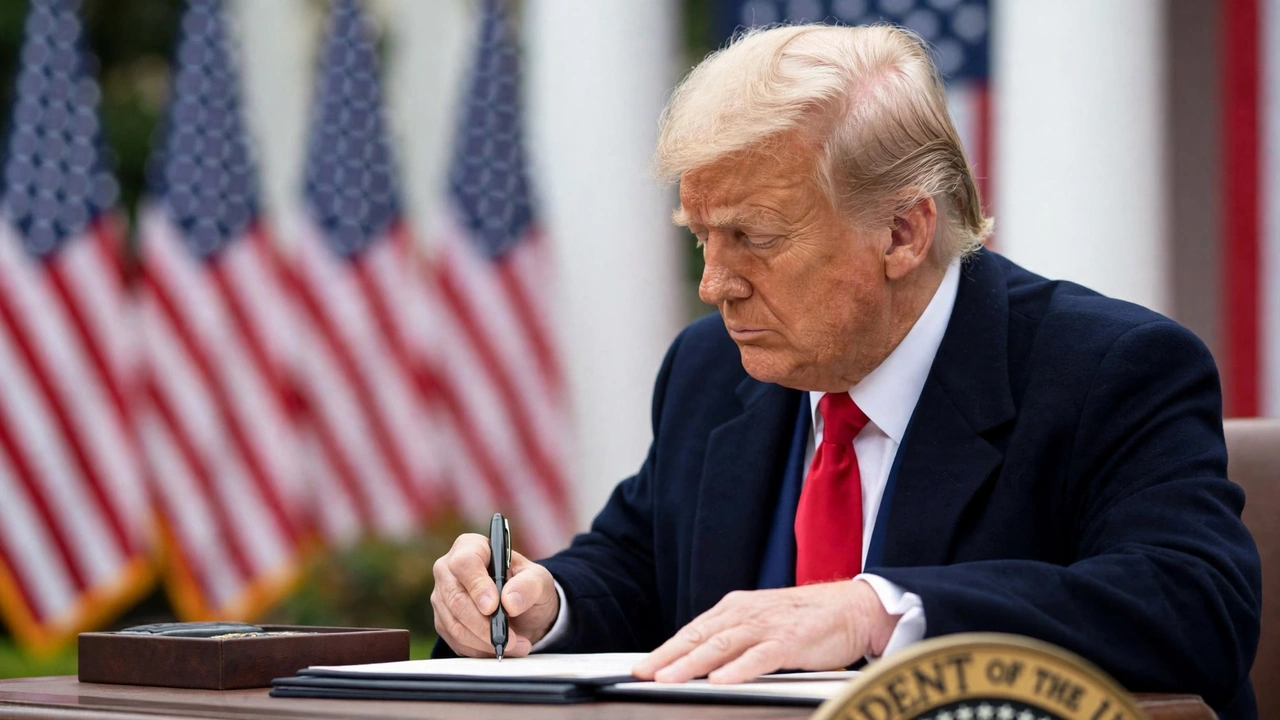
President Donald Trump signed the Retire Through Ownership Act into law on October 15, 2026, establishing a statutory framework that allows employee stock ownership plan (ESOP) fiduciaries to rely in good faith on qualifying independent appraisals when determining the value of privately held company shares.
The legislation, S. 2403, amends the Employee Retirement Income Security Act of 1974 (ERISA), addressing uncertainty over how trustees determine whether an ESOP pays an appropriate price for employer stock. The White House announcement confirms the signing.
The law incorporates valuation principles from Internal Revenue Service Revenue Ruling 59-60, a longstanding framework for evaluating closely held businesses. However, it does not eliminate fiduciary responsibilities, guarantee the accuracy of appraisals or establish automatic protection against lawsuits. That distinction is central to understanding what Congress changed and what remains subject to existing retirement-plan protections.
What Changed
Section 2 of the Retire Through Ownership Act adds language to ERISA Section 3(18), which defines adequate consideration for assets acquired or sold by retirement plans. For privately held securities without a generally recognized market, determining fair market value can require a detailed appraisal. Unlike publicly traded shares, whose prices can be observed through securities markets, closely held company stock may lack an independently observable trading price.
Under the enrolled legislation, an ESOP fiduciary may rely in good faith on a valuation prepared by an independent valuation expert or business appraiser using the principles and methodologies of IRS Revenue Ruling 59-60, including subsequent applicable IRS modifications.
The amendment provides an express statutory basis for that reliance rather than requiring trustees to operate solely within the existing general adequate-consideration framework and interpretations developed through enforcement and litigation.
The distinction matters because an ESOP transaction can involve the retirement plan purchasing shares from a business owner or other shareholder. An excessive purchase price could transfer economic value away from employees’ retirement accounts and toward the seller. The legislation addresses the valuation process, not the financial outcome of an individual transaction.
Valuation Rules
Revenue Ruling 59-60 identifies factors relevant to estimating the fair market value of closely held business interests. These include a company’s operating history, financial condition, earnings capacity, dividend-paying capacity, industry outlook, intangible assets and relevant comparisons with other businesses.
The methodology recognizes that a private company’s value cannot necessarily be determined from one financial measure. For example, two businesses reporting identical annual earnings may have different valuations because of their debt obligations, growth prospects, customer concentration or other material circumstances.
The new legislation does not establish a fixed earnings multiple, prescribe a universal discount rate or guarantee that two independent appraisers will reach the same conclusion. Instead, it ties permissible good-faith reliance to an independent professional’s use of established valuation principles.
This creates an important distinction between the methodology used to produce an appraisal and the ultimate price assigned to a company’s shares. A valuation may follow a recognized framework while still depending on assumptions about future performance, comparable businesses and economic conditions. Consequently, the legislation should not be interpreted as federal certification of any particular ESOP purchase price.
Fiduciary Protections
One of the most consequential provisions appears in Section 2(a), within the newly added ERISA Section 3(18)(B)(ii). Congress explicitly states that the amendment does not modify fiduciary obligations under ERISA Section 404.
Those obligations form a central part of the legal framework governing retirement-plan fiduciaries, including duties involving loyalty, prudence and the protection of plan participants’ interests.
The congressional record also documents the legislation’s preservation of the Department of Labor’s ability to issue regulations interpreting the new provision, while specifying that it does not expand the department’s preexisting regulatory authority over adequate consideration.
The distinction between valuation flexibility and continuing fiduciary responsibility also appears in broader debates over retirement investment rules, where regulatory changes can affect investment decisions without eliminating the obligations imposed on plan fiduciaries.
Taken together, these limitations narrow the law’s practical meaning. The amendment expressly permits good-faith reliance on a qualifying independent valuation, but it does not remove the fiduciary’s underlying legal responsibilities.
That is particularly important when assessing claims that the legislation creates an unconditional safe harbor against valuation-related litigation. The enacted language does not establish blanket immunity from lawsuits or declare that every appraisal prepared under Revenue Ruling 59-60 must be accepted as accurate.
Whether reliance satisfies applicable legal duties in a particular dispute may depend on the facts, the quality of the valuation process and the governing legal standards.
Effective Date
Section 2(b) establishes the effective-date provision. The amendments apply to the relevant adequate-consideration determinations made on or after the date of enactment, October 15, 2026.
That date is significant because the law’s application is tied to the determination described in the new provision, rather than automatically to the original establishment date of an ESOP. The legislation does not expressly establish a general retroactive rule validating every valuation or transaction completed before enactment.
For existing ESOPs, the relevant question is therefore not simply whether the plan was established before October 15. It is whether a particular valuation determination falls within the new statutory provision.
Trustees, independent appraisers and employers considering employee-ownership transactions must also distinguish the statutory effective date from any later interpretive guidance issued by the Department of Labor. The law is enacted; any additional regulations or implementation guidance are separate developments.
Employee Impact
Employee stock ownership plans allow workers to accumulate retirement benefits linked to ownership of their employer. Unlike a conventional retirement account invested across multiple publicly traded securities, an ESOP can hold a substantial interest in one employer, making the accuracy of the company’s valuation particularly consequential.
If employer shares are overvalued when purchased, the plan may pay more than their fair market value. If valuations are inaccurate at later measurement points, participants may receive misleading information about the value of their retirement interests.
The Retire Through Ownership Act addresses the process used to support fair market value determinations. It does not directly increase employee account balances, require employers to establish ESOPs or promise higher retirement distributions.
Its potential economic significance lies in reducing uncertainty surrounding qualifying independent appraisals while retaining existing fiduciary protections.
The distinction also matters for business succession. Owners considering a sale to employees through an ESOP may benefit from a more clearly defined valuation process, but the legislation does not guarantee that a proposed transaction will be financially appropriate.
More broadly, the measure reflects how changes in federal retirement policy can alter the legal framework for retirement-plan decisions without guaranteeing better investment outcomes for individual workers.
During the House debate on September 16, lawmakers from both parties supported the legislation as a response to longstanding uncertainty over ESOP valuations. The House approved S. 2403 by a vote of 401–14 after the Senate had previously passed the measure.
The resulting law provides a clearer statutory reference point for independent valuations, but its effect on future litigation, transaction costs and ESOP formation will depend on how fiduciaries, regulators and courts apply the amended framework.
For workers whose retirement savings depend on employer stock, the essential safeguard remains the same: company shares must be valued through a defensible process that respects the plan’s legal obligations and participants’ financial interests.