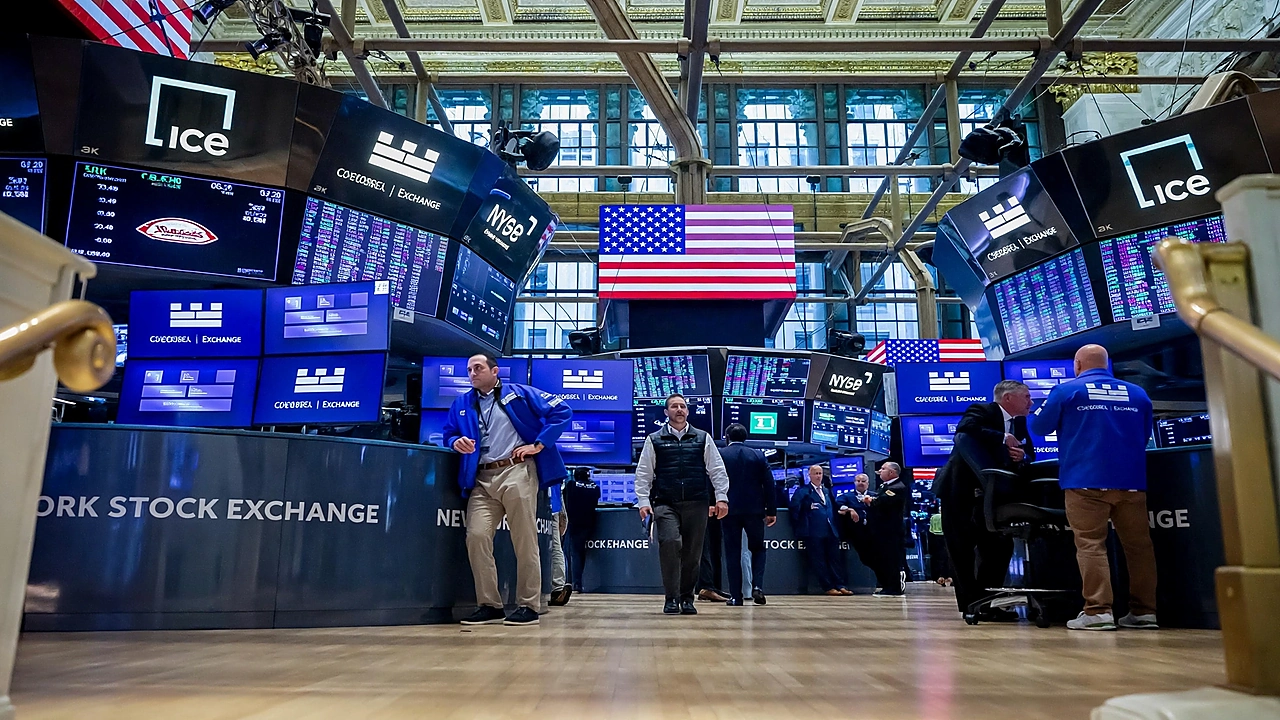
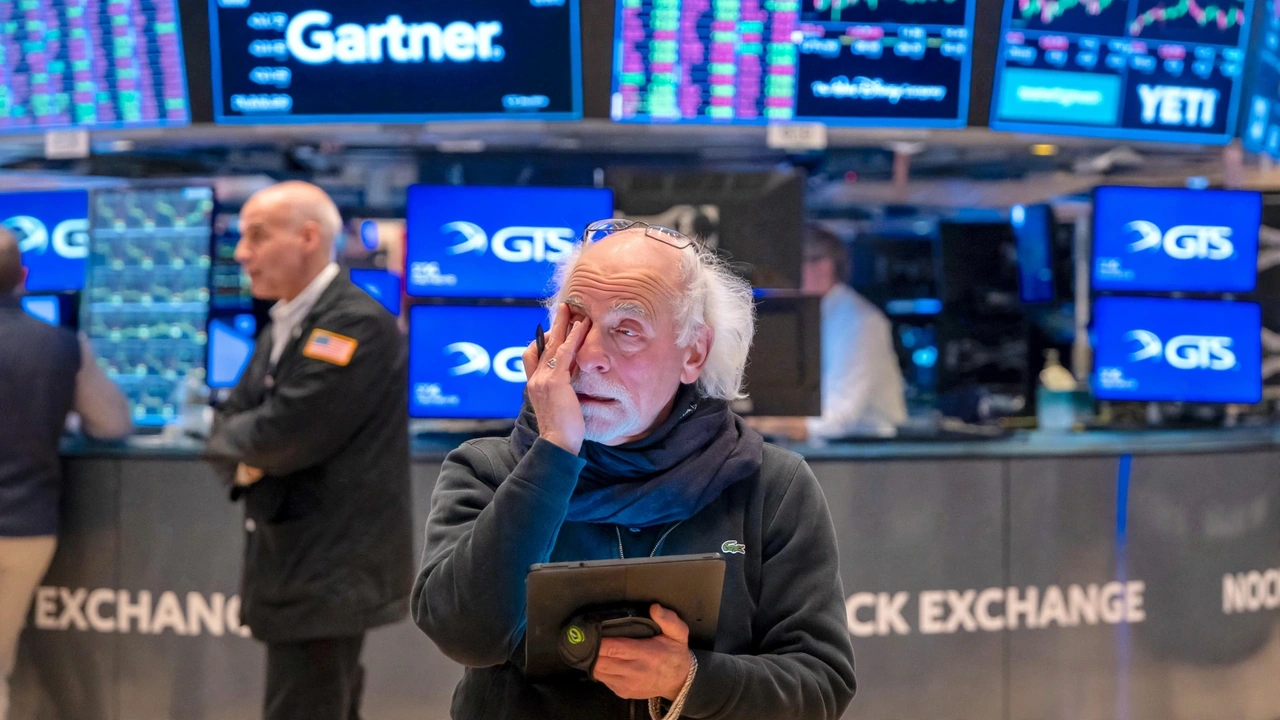
The S&P 500 fell 0.75% on Wednesday, September 23, as a sharp rise in U.S. Treasury yields and stronger-than-expected business activity pushed investors to reassess the outlook for interest rates.
The index closed at 7,706.05, while the Nasdaq Composite dropped 1.13% to 26,936.04 and the Dow Jones Industrial Average fell 0.68% to 51,511.59, according to Reuters’ September 23 Wall Street market report.
The move marked a clear change from the setup covered in Investozora’s September 23 stock-market report, which described a quiet opening with the Nasdaq near a record. By the end of Wednesday’s session, nine of the 11 S&P 500 sector indexes had declined, showing that the weakness extended beyond a narrow group of technology stocks.
Treasury yields moved sharply higher
The U.S. Treasury’s official daily par-yield data show how quickly the bond market changed. The 10-year Treasury yield rose from 4.96% on September 22 to 5.11% on September 23.
That is a 15-basis-point increase, calculated from the two official Treasury readings. The 2-year yield increased from 4.71% to 4.85%, while the 30-year yield rose from 5.29% to 5.40%. The figures are published in the Treasury’s September 2026 daily yield-curve data.
That broad rise matters for equities because Treasury yields influence the return investors can obtain from government debt as well as the discount rates used when valuing future corporate earnings.
Higher long-term yields can therefore make expensive stock valuations more difficult to sustain, even when economic growth itself remains firm. Investozora previously explained this connection in its coverage of Treasury yields and their effects on mortgages, savings and Social Security.
Wednesday’s bond move also pushed borrowing costs higher across the economy. Readers tracking the household side of the move can see the latest rate transmission in Investozora’s September 24 mortgage-rate coverage.
Stronger economic data changed the rate conversation
The catalyst was not simply the bond market itself. S&P Global reported that its flash U.S. Composite PMI rose to 58.4 in September from 56.0 in August, the strongest expansion since July 2021.
The survey also showed renewed employment growth and continuing cost pressures, with selling-price inflation remaining above levels consistent with the Federal Reserve’s 2% objective. S&P Global said the combination produced a more hawkish signal for interest rates.
That matters because the Federal Reserve has already moved policy higher. In its September 16 statement, the Federal Reserve raised the federal-funds target range to 3.75%–4.00%, its first increase since 2023.
The accompanying September Summary of Economic Projections gives investors the official framework for judging how policymakers see inflation, growth and interest rates evolving.
Investozora’s earlier Fed September rate-decision and 2027 outlook report provides the previous-state comparison: the September projections put the median federal-funds rate at about 4.1% at the end of 2026, above the June median of 3.8%.
That does not guarantee another rate increase, but it shows why stronger growth and persistent inflation can matter for stock valuations even after the September decision has already been made.
What markets are watching Thursday
The next question is whether the stronger economic picture continues to push yields higher or whether new data ease pressure on interest-rate expectations.
Thursday’s U.S. calendar includes the Department of Labor’s weekly unemployment-insurance claims report and the Census Bureau’s August New Residential Sales release. The Census Bureau’s official schedule lists August new-home sales for 10 a.m. Eastern on September 24.
Treasury supply is another test. The Treasury’s official auction schedule calls for a 7-year note sale Thursday, giving investors another real-time measure of demand for U.S. government debt as yields sit near their highest levels in years.
The broader schedule is available through the Treasury’s official auction calendar, while Investozora maintains a reader-friendly 2026 Treasury auction schedule. For now, the clearest change is straightforward: the S&P 500 entered September 24 after a 0.75% decline, while the official 10-year Treasury yield moved above 5% and the rate-sensitive parts of the market came under renewed pressure.
What remains unresolved is whether Wednesday’s jump in yields marks a temporary repricing or the start of a longer period in which stronger growth, inflation and Federal Reserve policy keep financial conditions tighter.