U.S. mortgage rates jumped sharply in the latest weekly reading, pushing the average 30-year fixed mortgage to 6.95%, up from 6.76% one week earlier and matching its highest level since January 2025.
Freddie Mac’s September 17 Primary Mortgage Market Survey showed the 30-year fixed rate increased 19 basis points during the week ending September 17. The average 15-year fixed mortgage also rose, climbing to 6.26% from 6.09%, a 17-basis-point increase. A year earlier, the comparable rates were 6.26% and 5.41%, respectively.
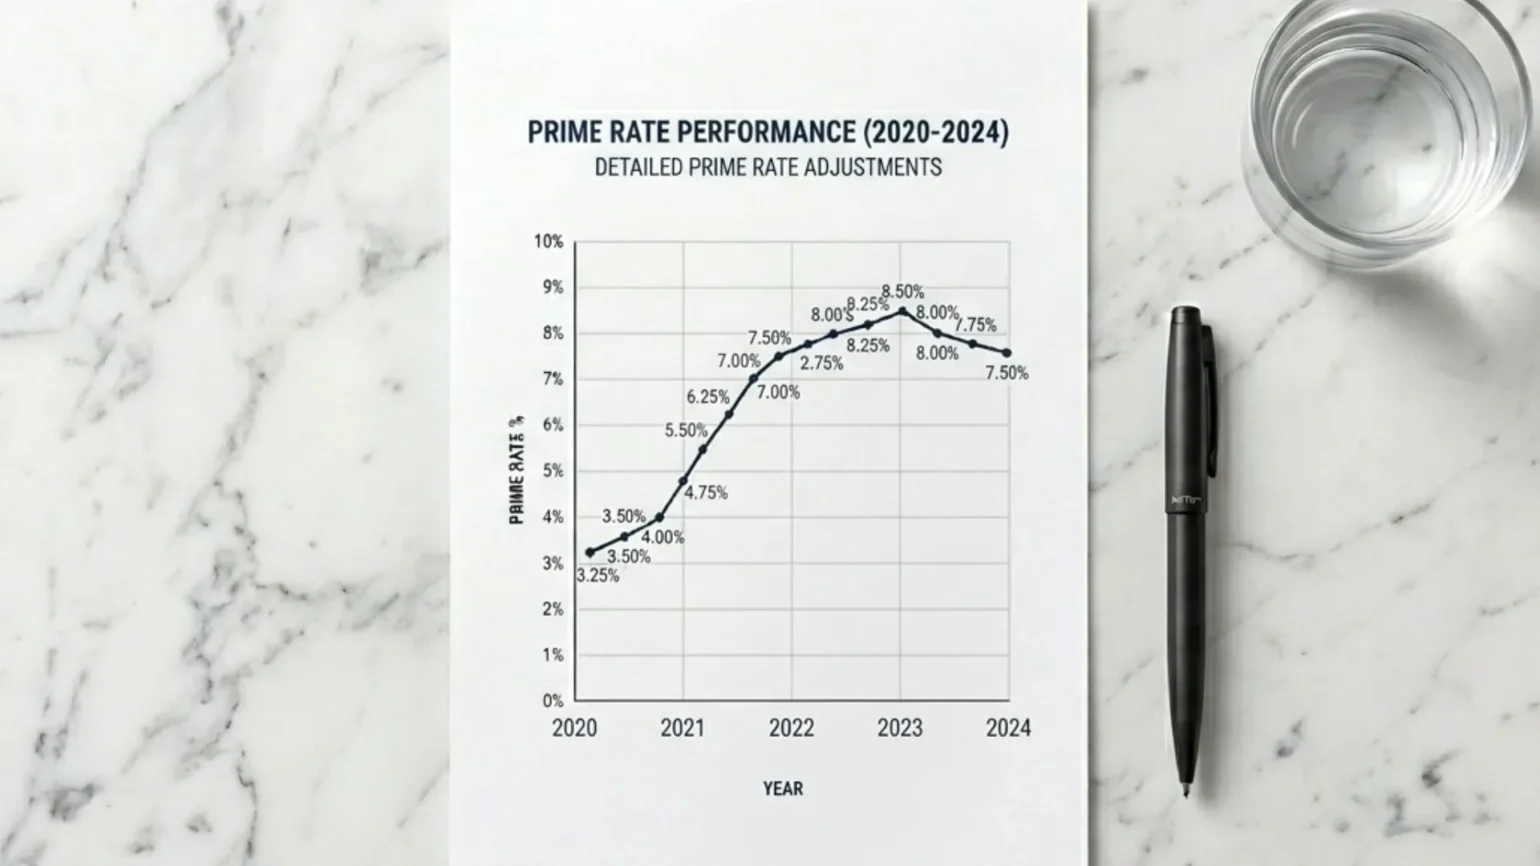
The latest increase extends a four-week climb in the 30-year rate. Freddie Mac’s 2026 weekly mortgage-rate archive shows the average moved from 6.66% on August 27 to 6.71% on September 3, 6.76% on September 10 and now 6.95%. That represents a 29-basis-point increase in three weeks.
Highest Since January
The 6.95% reading is the highest mortgage rate recorded by Freddie Mac since January 30, 2025, when the 30-year average was also 6.95%. One week earlier, on January 23, 2025, the rate stood at 6.96%, while the January 16 reading reached 7.04%, according to Freddie Mac’s 2025 PMMS historical data.
Rates subsequently moved lower for much of 2025 before falling as low as 5.98% in February 2026 and then rising again. That makes the latest move materially different from Investozora’s earlier report that mortgage rates had risen to 6.76% before the September Fed decision. The new Freddie Mac reading captures a further 19-basis-point increase and follows the Federal Reserve’s September policy action.
Payments Move Higher
The weekly increase also has a measurable effect on borrowing costs. An Investozora calculation shows that principal-and-interest payments on a $400,000, 30-year fully amortizing mortgage would rise from about $2,597 a month at 6.76% to $2,648 at 6.95%.
That is roughly $51 more per month, or about $609 more during the first year, solely from the 19-basis-point rate difference. The calculation excludes property taxes, homeowners insurance, mortgage insurance, closing costs and other fees.
Compared with the 6.26% Freddie Mac average recorded one year earlier, the same hypothetical $400,000 loan would cost about $182 more per month at 6.95%. Actual borrower rates can differ substantially because Freddie Mac’s benchmark is a national average rather than a guaranteed consumer quote.
Under Freddie Mac’s current PMMS methodology, the measure is based on thousands of mortgage applications submitted through its Loan Product Advisor system. The selected loans are conventional, conforming, owner-occupied purchase mortgages and generally represent borrowers with strong credit and loan-to-value ratios between 75% and 80%.
Yields Stay Elevated
The mortgage increase occurred as longer-term Treasury yields remained elevated. Treasury’s daily par yield curve data show the 10-year Treasury yield reached 5.01% on September 16, before falling to 4.94% on September 17. It returned to 5.01% on September 18.
Mortgage rates do not move one-for-one with the federal funds rate. Investozora’s guide to how Fed decisions affect mortgage rates explains that longer-term Treasury yields, inflation expectations, mortgage-market spreads, credit conditions and lender pricing also matter.
The Federal Reserve raised its federal funds target range by 25 basis points to 3.75%–4.00% on September 16, but that decision by itself does not establish that the Fed caused the full weekly mortgage-rate increase. The September FOMC statement confirmed the unanimous policy move.
Housing demand was already softening before the latest Freddie Mac reading. The Mortgage Bankers Association reported that total mortgage application volume fell 4.1% in the week ending September 11, with refinance applications down 9% and the seasonally adjusted purchase index down 1%. MBA’s September 16 Weekly Applications Survey attributed the weakness to a period of rising bond yields and mortgage rates.
The next Freddie Mac PMMS release is scheduled for Thursday, September 24. That reading will show whether the latest jump toward 7% continues, stabilizes or reverses as lenders respond to Treasury-market conditions following the Fed decision.