Brent crude oil futures fell below $94 a barrel early Thursday, November 5, before rebounding as investors reassessed expectations for a diplomatic resolution to the conflict involving the United States and Iran. ICE Futures Europe recorded January 2027 Brent at $93.57 a barrel at 01:48 GMT, followed by $94.25 at 05:37 GMT.
By 09:00 GMT, Brent had recovered further to $95.40, according to a time-stamped market report. The reversal matters to energy investors, businesses and households because oil prices are reacting to the possibility of improved supplies before any lasting resolution has been established.
The scale of the decline becomes clearer when comparing the same futures contract across two sessions. January 2027 Brent traded at $103.00 at 04:09 GMT on November 4, meaning its decline to Thursday’s $93.57 observation was $9.43 a barrel, or approximately 9.16%, based on an independent calculation.
Those are two intraday observations, not consecutive official settlement prices, and the percentage should not be presented as Thursday’s daily loss. The move extends the sharp repricing documented in Monday’s oil selloff, but Thursday’s recovery also illustrates how quickly expectations can reverse.
Why Oil Reversed
The latest selling has been accompanied by speculation that the outcome of the U.S. midterm elections could increase political pressure to pursue negotiations with Iran rather than further military escalation. That prospect has encouraged expectations of reduced risks to Middle Eastern energy production and shipping, although the market reaction cannot establish the intentions of either government.
Futures prices reflect traders’ assessments of future supply, demand and uncertainty rather than a direct measurement of today’s available crude. The distinction matters because a possible diplomatic breakthrough is not equivalent to an agreement that has already taken effect.
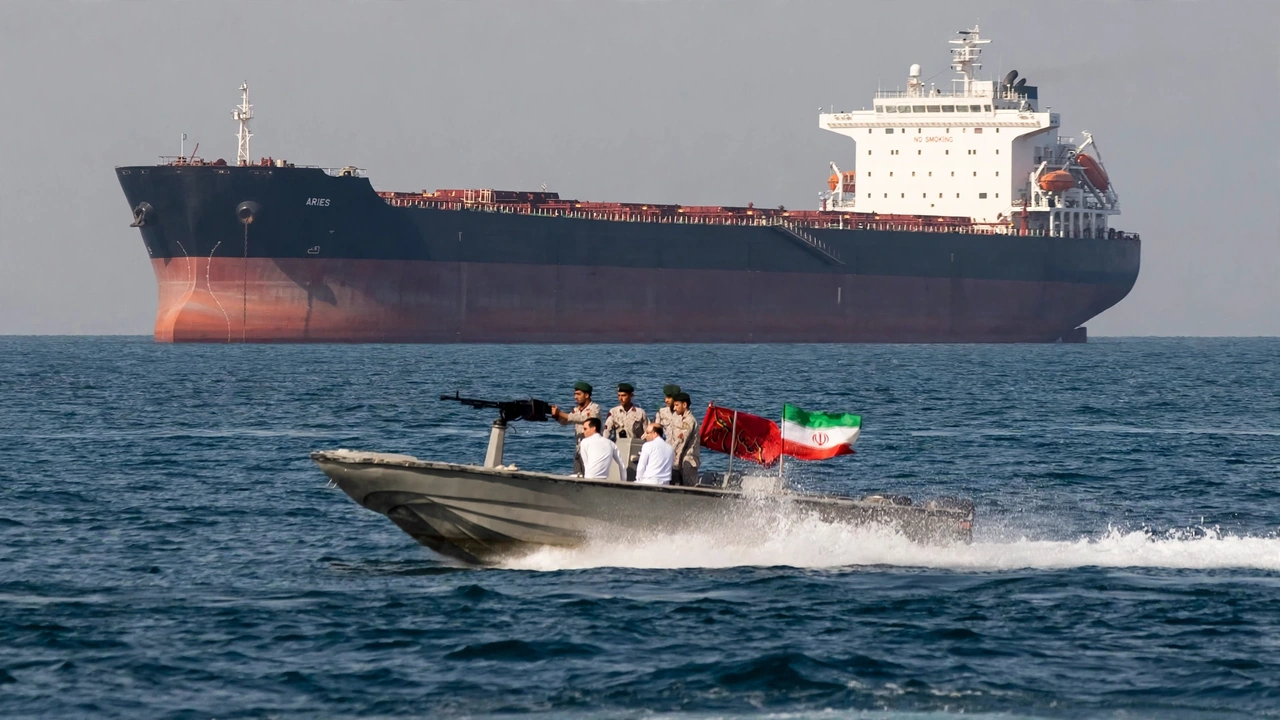
The change in sentiment follows a period when security concerns pushed prices sharply higher. A recent tanker attack near the Strait of Hormuz had reinforced concerns about the reliability of Gulf shipments, while Hormuz reopening conditions remained subject to unresolved political demands.
Those risks have not automatically disappeared because crude futures have fallen. The market is instead balancing the possibility of reduced disruption against the consequences of renewed hostilities. The same distinction applies to actual petroleum deliveries.
Expectations of Saudi export recovery can reduce concerns about available crude, but restoration of shipping capacity is a separate development from political expectations. Cargo availability, transit costs and refinery access determine whether improving conditions reach physical buyers. Without consistent evidence of those changes, a sharp futures decline cannot establish that the broader energy supply problem has ended.
Supply Remains Tight
The Strait of Hormuz remains central to the oil market because of the enormous quantities of petroleum that normally move through it. The U.S. Energy Information Administration’s shipping flow estimates show average crude oil and petroleum liquids movements declining from 21.6 million barrels per day in the fourth quarter of 2025 to 4.9 million in the second quarter of 2026.
Those historical quarterly averages demonstrate the scale of the earlier disruption but do not measure traffic on November 5. Recovering shipping volumes could improve supply conditions, although the pace and reliability of that recovery remain important.
More recent evidence shows that the physical market has improved without fully returning to its earlier condition. In a November 3 analysis, the EIA reported that global refinery crude inputs recovered by 1.8 million barrels per day during the third quarter after falling 4.8 million barrels per day in the second quarter.
The agency’s global refining data also showed third-quarter crude inputs remaining approximately 5% below their year-earlier level. That gap illustrates why an improvement from the worst period of disruption does not necessarily represent a complete normalization of supply.
Meanwhile, the latest U.S. inventory figures offer a counterweight to expectations of abundant crude. According to the EIA’s November 4 weekly inventory report, commercial crude stocks fell by 0.9 million barrels to 409.8 million barrels during the week ending October 30, leaving inventories approximately 4% below their five-year seasonal average.
Gasoline inventories declined by 0.2 million barrels, while distillate stocks fell by 3.6 million barrels and stood 13% below their five-year average. The drawdowns contrast with falling futures prices, although a single weekly U.S. report cannot establish the global supply balance.
The difference between expectations and physical supply also matters for producers. Seven major OPEC+ members recently maintained their December production targets, leaving their agreed output levels unchanged rather than announcing another increase.
Production targets, actual output, available export routes and delivered cargoes are separate measures. Consequently, neither Thursday’s futures prices nor the policy decision alone establishes how much crude will reach importing countries in the coming weeks.
Gasoline Price Impact
For American drivers, lower crude oil prices create the possibility of reduced fuel costs, but Thursday’s decline does not guarantee an immediate change at filling stations. The EIA’s weekly gasoline survey placed the national average regular gasoline price at $4.153 a gallon on November 2, compared with $4.269 on October 26.
That represents an observed decline of 11.6 cents per gallon before Thursday’s latest crude-price movement. It is therefore incorrect to attribute the entire existing reduction at the pump to developments on November 5.
A practical calculation illustrates the difference between the price of crude and what drivers actually pay. A hypothetical 15-gallon purchase at the November 2 national average would cost approximately $62.30, compared with $64.04 at the October 26 average, a saving of $1.74 before rounding the totals.
That calculation uses two EIA retail-price observations and does not forecast an additional saving from the latest oil selloff. The distinction is particularly important after the elevated October gasoline prices experienced by American households.
The transmission from crude prices into gasoline and diesel is neither immediate nor perfectly proportional. The EIA’s fuel pricing methodology identifies crude acquisition costs, refining, distribution, marketing and taxes as separate components of retail prices.
Refinery margins and local fuel availability can prevent pump prices from declining by the same percentage as oil futures. For households, the meaningful evidence of relief will be sustained reductions in actual retail fuel prices rather than a single trading-session movement.
Investor Exposure
The implications also differ across the energy industry. Oil producers can face pressure on revenue expectations when crude prices decline, while airlines, transportation operators and some manufacturers may benefit from lower future fuel expenses if the decline persists.
Refineries occupy a more complicated position because their performance depends on both the cost of crude inputs and the selling prices of petroleum products. Earlier increases in physical cargo premiums show why futures prices do not necessarily represent the delivered cost of crude for every buyer.
For investors, the critical question is whether the market is pricing a durable improvement in supply or a temporary reduction in perceived geopolitical risk. Futures contracts, energy-company shares and retail gasoline prices respond to different mechanisms and do not have to move together.
A decline in crude is not sufficient evidence that a particular airline’s earnings will improve or that an oil producer’s shares must fall. Those conclusions would require company-specific cost exposure, operating information and additional market evidence.
The U.S. government’s emergency oil reserves add another consideration. The Department of Energy announced further implementation of its previously established reserve-release commitments in September, while the size of the emergency crude reserve has become an important part of the broader energy-security discussion.
The department’s reserve release announcement describes actions intended to support global supply stability, but reserve deliveries do not establish that geopolitical risks have been eliminated. Actual releases, remaining stockpiles and changes in commercial inventories must be evaluated separately.
What Happens Next
The next decisive developments will involve actual diplomatic commitments, the security of Strait of Hormuz transit and measurable changes in petroleum supply. Traders will also be watching future EIA inventory reports, refinery activity and gasoline prices for evidence that lower crude prices are translating into more stable physical-market conditions.
An agreement that materially restores shipping would support a different interpretation from a renewed escalation that interrupts deliveries. Neither outcome can be established from Thursday’s price movement alone.The November 5 reversal demonstrates both the power and the limitations of changing expectations in oil markets.
Brent’s brief drop below $94 showed how rapidly traders could reduce the price they were willing to pay for near-term crude exposure, while its subsequent recovery highlighted uncertainty surrounding that judgment.
For businesses and households, the most important question is whether easing geopolitical concerns eventually produce reliable fuel supplies and lower delivered energy costs. Until those changes are independently demonstrated, the latest oil selloff is evidence of a market repricing, not confirmation of lasting peace or permanent consumer savings.