Gold prices fell below $4,100 per ounce on Friday, November 6, 2026, reversing part of Thursday’s recovery as rebounding oil prices revived concerns about inflation and the Federal Reserve’s interest-rate outlook. Spot gold declined 1.1% to $4,044.09 per troy ounce at 05:01 UTC, according to Reuters, while December U.S. gold futures dropped to $4,053.30. January Brent crude futures simultaneously climbed 1.31% to $99.58 a barrel at 05:04 UTC. The contrasting moves matter to gold investors, energy-sensitive businesses and households, although neither establishes where prices will finish the trading day.
The reversal came less than a day after gold reached $4,146.63, its highest intraday level since October 20, as the dollar weakened and Treasury yields declined. Thursday’s gold price rally had strengthened hopes of a sustained recovery following several volatile sessions. Friday’s decline instead illustrates how quickly the market can reassess inflation risks and the attractiveness of non-yielding assets. It does not, by itself, establish that gold’s broader recovery has ended.
Reversal in Numbers
The most revealing comparison is between two observations of the same spot-gold market. Gold traded at $4,100.27 at 19:05 UTC on Thursday and $4,044.09 at 05:01 UTC on Friday, a decline of $56.18 per ounce, or approximately 1.37%, according to an independent calculation from Reuters-reported prices. Compared with Thursday’s $4,146.63 intraday high, the Friday quotation was $102.54 lower, a 2.47% retreat. The latter is a peak-to-quotation comparison, not a daily closing-price return.
Oil moved in the opposite direction over its latest settlement-to-quotation window. January Brent futures rose from Thursday’s $98.29 settlement to $99.58 early Friday, while U.S. West Texas Intermediate futures climbed from $90.52 to $91.38. The following comparison uses the same instrument within each row, although the gold and oil observation windows are different and should not be treated as proof of a direct relationship.
| Instrument | Thursday reference | Friday quotation | Calculated change |
|---|---|---|---|
| Spot gold, per troy ounce | $4,100.27 | $4,044.09 | −1.37% |
| January Brent, per barrel | $98.29 | $99.58 | +1.31% |
| WTI crude, per barrel | $90.52 | $91.38 | +0.95% |
Thursday’s oil settlements followed an unusually turbulent period in energy markets. Brent gained $3.67 that day after Wednesday’s sharp decline, and Friday’s advance extended the recovery for a second session. However, Brent was still on course for a weekly decline of roughly 12% at the Friday-morning observation, demonstrating that a rebound can coexist with a much larger preceding selloff. The sequence is clearer when viewed alongside Thursday’s Brent price rebound and Monday’s oil market selloff.
Oil and Gold
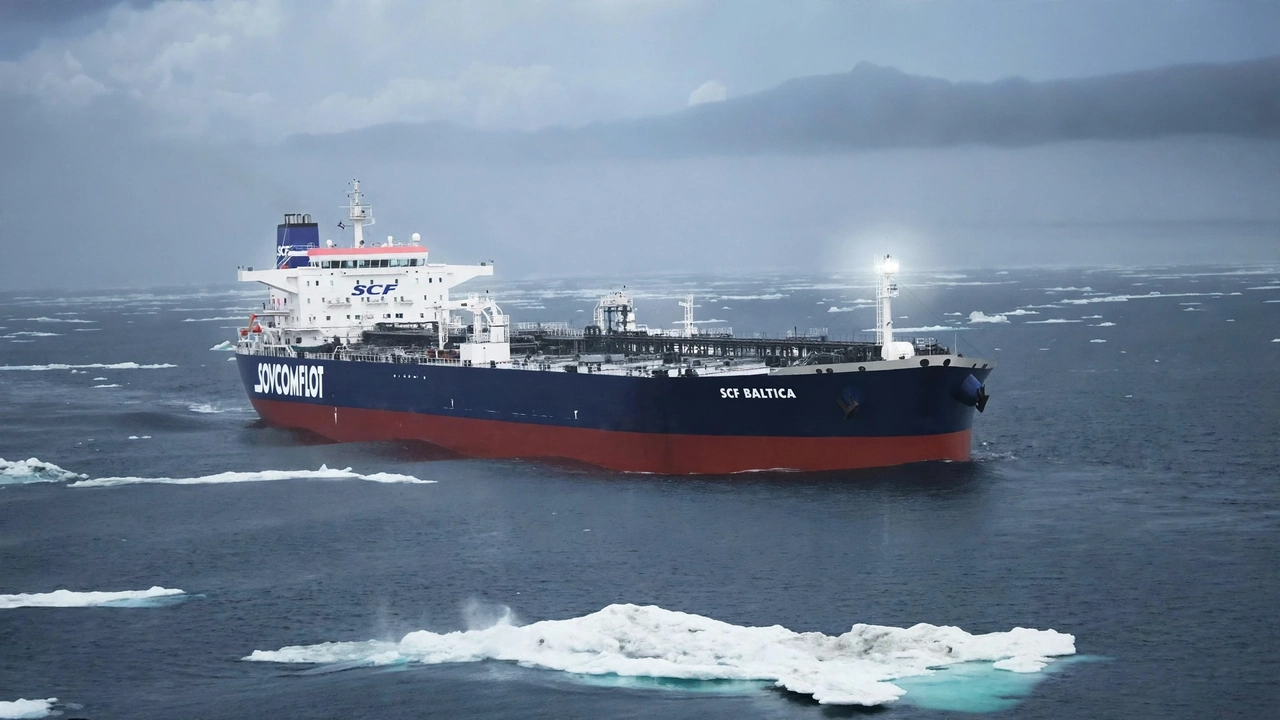
The renewed strength in crude came amid continuing concerns about the security of Middle Eastern shipping routes. The United Kingdom Maritime Trade Operations organization recorded an incident on November 5 involving a tanker reportedly struck by unidentified projectiles north of Qatar, with the extent of damage and the crew’s condition unconfirmed in its initial notice. Its official maritime incident reports also document earlier incidents near the Strait of Hormuz. Those reports provide direct evidence of maritime-security risks, while the market’s pricing response remains an interpretation rather than a measured loss of oil supply.
The same uncertainty has repeatedly pushed traders to reconsider how quickly regional oil flows might stabilize. Earlier Hormuz tanker attacks had already demonstrated how shipping-security developments could accompany substantial movements in crude futures. Nevertheless, a higher futures quotation does not establish that every refinery faces an immediate shortage or that retail fuel prices will rise by the same percentage. Physical supply, transport costs, inventories and local market conditions determine how sustained disruptions affect individual buyers.
Gold faces a different calculation because the metal produces no interest income. When rising energy prices reinforce expectations of persistent inflation, investors may anticipate tighter monetary policy or higher interest rates, increasing the opportunity cost of holding bullion. In its October Fed statement, the Federal Reserve maintained its federal funds target range at 3.75%–4%, while two officials favored a quarter-percentage-point increase. That decision, also examined in the October rate decision, provides the policy context for Friday’s market uncertainty, not evidence that another increase has already been decided.
The explanation also has an important limitation: gold does not always decline when oil rises. Government bond yields, currency movements, equity-market losses, portfolio positioning and demand for financial protection can pull bullion in competing directions. The Treasury’s official daily yield data show the 10-year nominal yield falling from 4.90% on November 4 to 4.84% on November 5, a six-basis-point decrease. Those observations do not cover Friday’s full trading window, making it inaccurate to attribute Friday’s gold decline to a verified rise in Treasury yields; the distinction between nominal and real rates is explored in the Treasury yield framework.
Investors and Households
For someone holding physical gold, Friday’s decline changes the market value of the metal without necessarily producing a realized loss. A hypothetical holding of 10 troy ounces would have a spot-value difference of $561.80 between Thursday’s 19:05 UTC observation and Friday’s 05:01 UTC quotation, calculated as 10 multiplied by $56.18. That is an illustrative mark-to-market change, not a claim about any investor’s purchase price or actual proceeds. Transaction spreads, dealer premiums, taxes and the structure of a gold investment can substantially alter the outcome.
Physical buyers also need to distinguish international spot quotations from retail prices. The United States Mint’s bullion buying guidance emphasizes understanding market prices, premiums and the seller before making a purchase. Consequently, a 1.37% change in the quoted spot price does not guarantee an identical change in the resale value of a particular coin or bar. Gold’s October price decline provides another example of why the timing of an observation matters when comparing investments.
For households and businesses, oil presents a more immediate potential cost channel, although the transmission is not automatic. The Bureau of Labor Statistics reported in its September inflation report that consumer prices increased 3.7% over 12 months, while the energy index rose 20.4%. Those figures establish the inflation backdrop, but Friday’s crude futures cannot be used to calculate a new consumer inflation rate. Earlier wholesale gasoline increases illustrate why energy-related price movements deserve attention beyond commodity trading.
The exposure is particularly relevant to households reliant on heating oil and businesses with substantial transportation or fuel expenses. In its October energy market outlook, the Energy Information Administration projected that U.S. households primarily using heating oil would spend approximately 21% more on that fuel during the 2026–27 winter than during the previous winter. That forecast was prepared using information available by October 1, so it does not incorporate Friday’s market reversal. Subsequent oil prices, weather and actual fuel consumption could produce different outcomes.
What Comes Next
Investors were awaiting the October U.S. employment report, scheduled for release at 08:30 a.m. Eastern Time on Friday, November 6, or 13:30 UTC. The official employment release schedule confirms the timing, making the report a clearly identifiable event after the early-Friday gold and oil observations discussed here.
Employment and wage data may influence expectations about Federal Reserve policy, but the direction and magnitude of any market response cannot be established before the figures are released. Readers following the next major U.S. releases can consult the economic calendar for the scheduled sequence.
For gold, the central question is whether the retreat below $4,100 persists as investors reassess interest rates, the dollar and the demand for defensive assets. For oil, attention remains on whether shipping conditions improve sufficiently to reduce the risk premium associated with disrupted Middle Eastern routes.
A sustained increase in energy costs could complicate the inflation outlook, but Friday’s rebound alone cannot establish that outcome. As of the verified early-Friday observations, gold had surrendered part of Thursday’s advance while crude recovered further from its earlier selloff—two market developments whose longer-term significance remains unresolved.