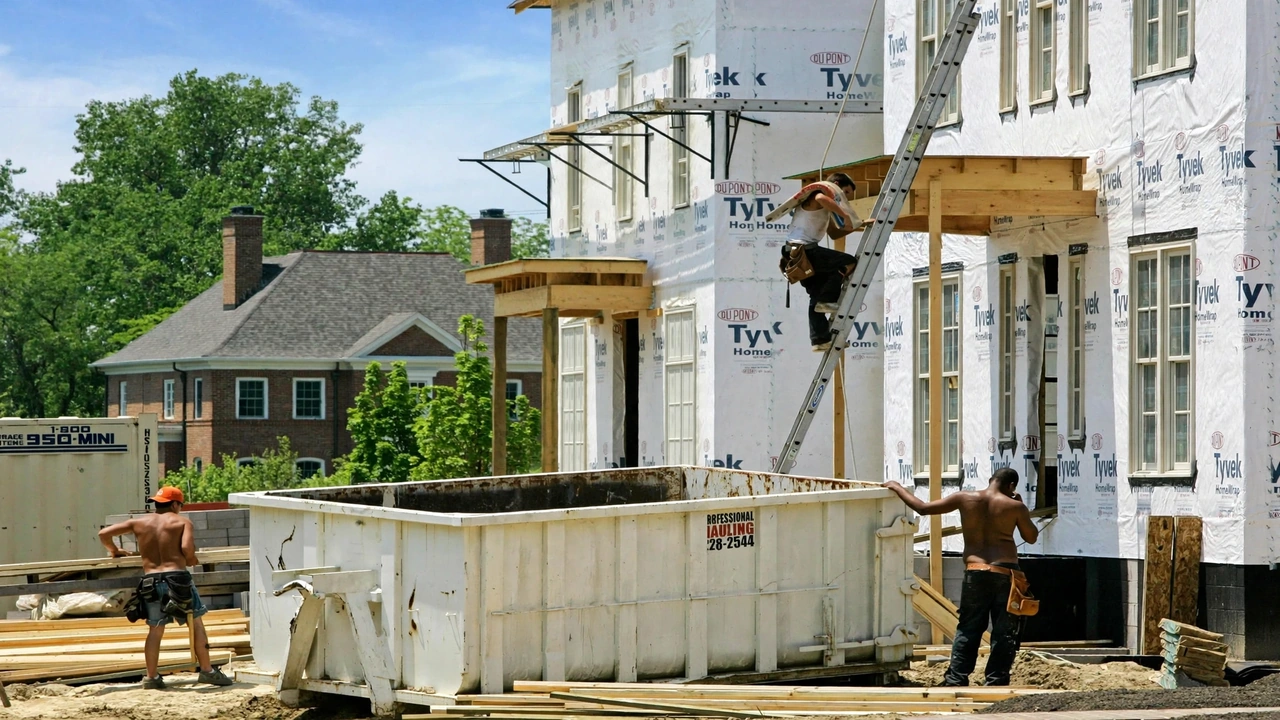
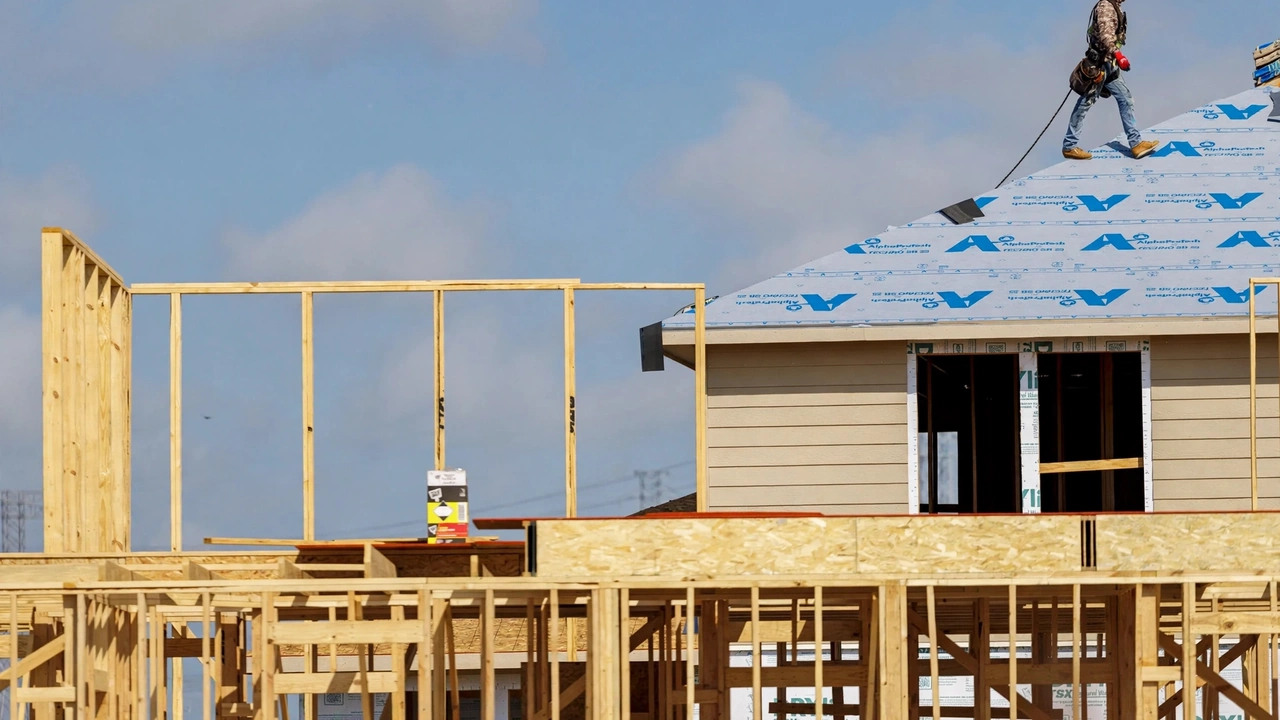
U.S. homebuilding slowed in September 2026, with housing starts falling 5.2% to a seasonally adjusted annual rate of 1.221 million units, as single-family construction weakened and starts in larger apartment buildings declined.
The estimate, released Tuesday, October 20, by the U.S. Census Bureau and Department of Housing and Urban Development, was down from a revised August rate of 1.288 million units. Starts were also 7.4% below the September 2025 rate of 1.319 million, according to the agencies’ September housing report.
However, the reported monthly and annual declines were not statistically significant at the 90% confidence level, meaning the data do not conclusively establish a decrease in underlying construction activity. The report also revealed a contrast: building permits were nearly unchanged even as builders broke ground on fewer homes.
Construction Breakdown
Single-family housing starts fell 4.6% to an annual rate of 859,000 units, down from a revised 900,000 in August. The decline interrupted the increase reported in August, when single-family construction had initially been estimated at 918,000 units.
Starts in buildings containing five or more units declined 7.2% to 349,000, compared with 376,000 in August. They were 25.9% below September 2025. The combined picture indicates weaker reported activity across both major housing categories, although the estimates carry substantial statistical uncertainty.
Regional performance was uneven. Housing starts in the Northeast remained at an annual rate of 114,000, while the Midwest increased 4.3% to 158,000. The South, the largest region for residential construction, recorded a 6.1% increase to 714,000. In contrast, starts in the West dropped 23.2% to 235,000.
Those regional figures show that the national decline was not uniform. Particularly in the West, however, the reported monthly change should not be interpreted without considering its wide confidence interval.
Permits Hold Steady
Building permits, an indicator of planned construction, declined just 0.2% to a seasonally adjusted annual rate of 1.400 million units, compared with a revised 1.403 million in August. Single-family permits fell 4.0% to 845,000, while permits for buildings with five or more units increased 5.9% to 503,000, according to the Census Bureau’s permit estimates.
This divergence matters because permits and starts measure different stages of development. A permit authorizes construction, while a housing start records when construction begins. A newly issued permit does not guarantee that work will start immediately.
The weakness in single-family permits suggests that the slowdown extended beyond projects already breaking ground, although monthly permits alone cannot predict future construction levels.
Residential construction also operates within a financing environment shaped by mortgage costs and builder economics. Investozora’s earlier reporting on September mortgage rates and the mortgage rate outlook provides context for borrowing conditions. However, the Census report does not establish mortgage rates as the direct cause of September’s decline.
Completions Rise
Housing completions increased 2.2% to an annual rate of 1.192 million units, up from a revised 1.166 million in August. Single-family completions declined 2.4% to 840,000, while completions in buildings containing five or more units increased 14.9% to 339,000.
The difference between starts and completions illustrates how construction activity at different stages can move in opposite directions. Homes completed during September generally began construction earlier, while new starts represent projects entering construction.
Completions nevertheless remained 14.0% below September 2025, indicating that the reported monthly improvement did not reverse the broader year-over-year weakness in finished housing supply.
For homebuyers, fewer starts do not automatically mean fewer homes available immediately. New construction must progress through multiple stages before becoming finished housing, and local inventory conditions can differ substantially from national averages.
Interest-rate developments remain relevant to housing affordability, but the relationship between Federal Reserve policy and mortgage borrowing costs is not one-for-one. Investozora’s explanation of Treasury yields provides additional context.
What Comes Next
The September housing figures are preliminary and subject to revision. August’s estimate of total starts was revised upward from 1.275 million to 1.288 million, while the August single-family estimate was revised downward from 918,000 to 900,000.
Those revisions reinforce why one month’s movement should be treated cautiously. The Census Bureau also warns that it can take approximately six months to establish an underlying trend in housing starts because monthly estimates are volatile.
The next New Residential Construction report, covering October 2026, is scheduled for November 18, 2026, at 8:30 a.m. Eastern Time, according to the official release schedule. It will provide another reading on whether September’s weaker estimated starts developed into a sustained slowdown or proved to be temporary.